

Super funds lead profits as major banks top tax bill rankings
By Carlos Tse
20 November 2026 • 3 minute read
Among Australian companies, the big banks paid the largest amount of income tax, followed by mining companies, with Australian superannuation earning the highest pre-tax profit, out of 382 public country-by-country (CbC) reports, released by the ATO on 12 November.
The most profitable Australian companies before income tax were led by superannuation funds, with AustralianSuper at $35.5 billion, the Australian Retirement Trust at $33.5 billion, Aware Super at $20.5 billion, Construction and Building Unions Superannuation Fund at $17.9 billion, UniSuper at $16.2 billion, followed by CommBank at $11.6 billion.
Further, within this tranche, CommBank paid the highest amount of income tax over the year out of the Australian companies on the list at $3.6 billion.
In the rankings for the most tax paid by Australian companies, the blue-chip bank was followed by other big banks and mining companies, with Westpac having paid $3.02 billion, NAB $2.46 billion, ANZ $1.67 billion, Hancock Prospecting $1.51 billion, and Fortescue $1.63 billion.
However, one tax expert noted that since the ATO only published fewer than 400 reports for companies with a 30 June 2025 financial year-end, the results are not representative of the full population.
“The aggregation of data into a ‘Rest of World’ category means there is limited analysis that can be done on the specific jurisdictional performance of entities.
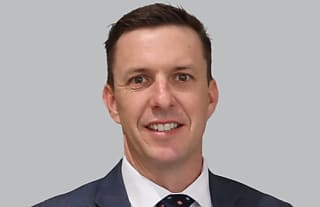
“Value will likely emerge as further tranches are published and trends can be examined over multiple reporting periods,” RSM Australia transfer pricing and international tax partner, Brad O’Donnell (pictured), told Accounting Times.
O’Donnell told the brand that he was surprised by how differently groups approached narrative disclosures in this first tranche.
“Some businesses provided quite detailed explanations of their approach to tax and tax governance, while others provided relatively limited commentary,” O’Donnell said.
“At the moment there is no real market practice for what ‘good’ looks like or even to what the public expects, and so it will be interesting to see whether those disclosures converge as businesses compare themselves with their peers.”
The significance of the publication
These reports were submitted under the nation’s Public CbC reporting regime, which requires large businesses with operations in Australia to publicly disclose tax and financial data about their business group annually.
These publications follow the ATO’s release of its annual corporate tax transparency (CTT) report in October, which gives a “relatively simple Australian picture of income, taxable income and tax payable,” O’Donnell said.
“Taken together, the two regimes significantly expand the information available about the tax affairs of large businesses operating in Australia,” he said.
“Equally, mismatches between the different public datasets are likely to attract questions, so businesses increasingly need to consider their tax disclosures as one connected story rather than separate compliance exercises.”
O’Donnell stressed that businesses need to consider how the numbers in their Public CbC reports will look without detailed context available.
“Reporting entities should therefore benchmark their proposed disclosures against the first tranche, identify figures that could attract attention, and make sure their tax narrative properly explains the commercial story behind the numbers.
“Consistency with financial statements, existing tax transparency statements (including the R&D Tax Transparency Statement), confidential CbC reporting and other public disclosures will also become increasingly important.”
The reporting obligations require large multinational groups with over $10 million in Australian-sourced turnover to report financial and tax information for each jurisdiction in which they operate. The rules apply to reporting periods beginning on or after 1 July 2024, with the first reports due at the end of June 2026.
They have 12 months from the end of their relevant reporting period to meet their annual Public CbC reporting obligations.
With the publication of these reports, the broader public now has access to the Australian tax position of larger businesses and can obtain a much broader view of the global taxable presence of an organisation, O’Donnell said.
“While this information has been available to Tax Authorities since approximately 2017 with the introduction of Private CbC Reporting under the OECD/G20 BEPS Action 13 initiative, it is now in the public realm via the Australian and European Union’s Public CbC Reporting initiative,” he added.
To ATO acting deputy commissioner Michelle Sams, this marks an important milestone in corporate tax transparency.
“These reports provide the public greater visibility of the global operations and tax disclosures of large businesses operating in Australia,” Sams said.
“As more reports are published over time, the data will provide a more comprehensive picture of the global operations and tax disclosures of large businesses operating in Australia.
“Public CbC reporting enables the public to make a better assessment of whether a reporting entity’s economic presence in a jurisdiction aligns with the amount of tax they report and pay in that jurisdiction.”
Want to see more stories from trusted news sources?
Make Accounting Times a preferred news source on Google.
Click here to add Accounting Times as a preferred news source.
Carlos Tse
AUTHOR
Carlos Tse is a graduate journalist writing for Accountants Daily, HR Leader, Lawyers Weekly.
KNOW MORE