

Tax partner flags potential tax traps with running businesses at home
By Carlos Tse
25 September 2026 • 2 minute read
With the CGT changes coming into effect on 1 July 2027, which introduce valuation requirements and changes for business owners running out of a home, one tax partner explained the options owners have to use their house as their premises.
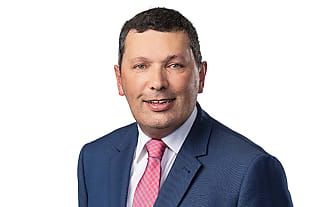
Speaking with Accountants Daily, HLB Mann Judd tax consulting partner Peter Bembrick (pictured) said that over the years, it has become easier to carry out a business from home due to emerging technologies that enable remote work.
“It's easier to carry on a business from home just because of technology and the way things work these days,” Bembrick told the brand.
While these technologies make owning a business more accessible, this has expanded the grey area for tax-deductible business expenses, he said.
“That's what makes this a lot more grey. Years ago, it would have been much clearer whether you run a business or not,” he said.
Compared to a home-run business where a proportion of the house is genuinely used to conduct business (with rooms not readily adaptable for domestic use), some business owners may only be eligible for working from home deductions — a narrower range of expenses — if they cannot prove to the ATO that the portion of the house is genuinely used for business purposes, Bembrick said.
The potential solution here, Bembrick noted, is to seek a private ruling with the ATO to claim main residence exemption for the business.
“If you think you've got a good case and you want a bit more certainty [obtaining a ruling] it takes a bit of time, and there's a bit of cost involved. Getting a ruling means you at least have some certainty from the ATO that you've got a private ruling saying, ‘this is okay as long as you stick to the facts and don't change’,” Bembrick said.
“The downside of getting a ruling is if the ATO says no, then you have to follow what they said, so it isn’t something you do lightly, but it is an option to get that certainty.”
While the ATO has a stringent approval process for obtaining a private ruling, an ambiguous position may be a sign that a private ruling may be the best option.
“At the end of the day, it's a factual thing, but facts are not always clear-cut. If a position isn’t clear-cut, then another thing you can consider is getting a ruling from the ATO,” Bembrick said.
“Where the ATO would push back is that they would say you’re not really running a business; you’re just working from home.”
“It can be very subjective … it’s so fact-specific, it's hard to give too many guidelines on what to do and what not to do.”
Where a business is not a sole trading entity, and operating from a house is not an option, companies can pay rent for the property, which can be deducted as a business expense, he added.
“There's probably more incentive for someone if they are renting to try and claim that because if you're not the owner, you don't have the flip side of having to then use your CGT exemption on the house … That's a good situation to be in; there's not really downside to that,” Bembrick said.
“They'd have to then essentially [get] their company to pay rent for the portion of the house they're using. The company would obviously have that as a deduction expense against its business income, and they might pay the outgoings,” he concluded.
Want to see more stories from trusted news sources?
Make Accounting Times a preferred news source on Google.
Click here to add Accounting Times as a preferred news source.
Carlos Tse
AUTHOR
Carlos Tse is a graduate journalist writing for Accountants Daily, HR Leader, Lawyers Weekly.
KNOW MORE